Key takeaways
- Diwali 2026 spending is projected at $83 billion — up from a record $69 billion in 2025, and on course to overtake Black Friday and Cyber Monday combined in total retail value for the first time.
- 85% of Diwali trade happens in physical stores. In 2026, grocery is projected to grow 48–50%, beauty and personal care 35–40%. Electronics are losing share as smartphone prices rise.
- The $83 billion figure captures India’s domestic market alone and does not include an estimated 32 million diaspora consumers across the US, UK, Canada, the Gulf and elsewhere who celebrate with equal enthusiasm and, in many cases, deeper pockets.
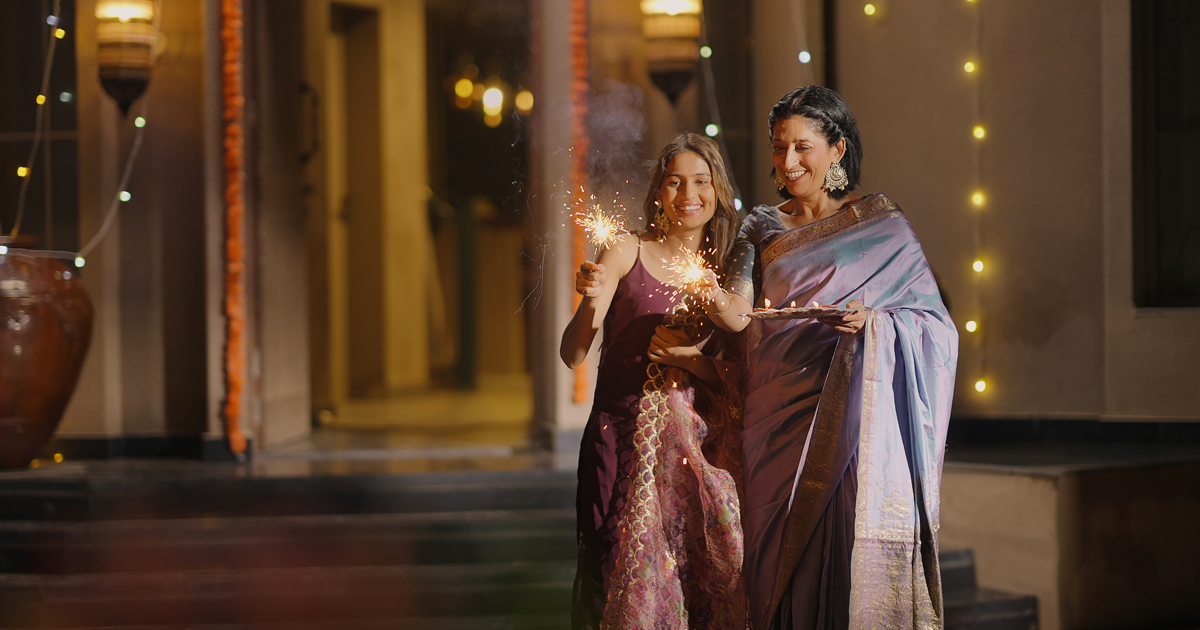
Every year, the global retail calendar makes the same omission. Black Friday commands wall-to-wall coverage. Singles’ Day in China draws exhaustive sales analysis from every major research house. Diwali — which in 2025 generated $69 billion in consumer spending across India — is treated as a regional event.
That changes when the numbers are reviewed and taken seriously. In 2025, the Navratri-to-Diwali festive window delivered a 25% increase on the year before, the highest festive turnover ever recorded in the country. That same year, Black Friday and Cyber Monday pulled in a combined $75 billion in US retail sales. Fast forward to 2026, and Diwali is set to cross a historic threshold: with the Confederation of All India Traders (CAIT) projecting this season to exceed ₹7 lakh crore — approximately $83 billion — Diwali 2026 spending is on course to overtake Black Friday and Cyber Monday combined in overall sales for the first time ever.
Where does the money go?
The scale of Diwali spending is striking enough. What it’s spent on tells a more useful story for retailers. Despite India’s rapid e-commerce growth, brick-and-mortar still accounts for approximately 85% of total festive trade. This is a season built on physical retail — on markets, jeweler stores, electronics showrooms, and clothing shops that families visit in person, often more than once across the five-day celebration.
According to CAIT’s post-season data, food and grocery accounted for 12% of total Diwali retail spend in 2025, gold and jewelry 10%, electronics 8%, and garments and gifts 7%. Just to be clear, we are not talking about impulse buys. These are purchases planned weeks in advance, often tied to specific cultural rituals: gold bought on Dhanteras, new clothing worn on Diwali day, sweets and gifts exchanged across households.
E-commerce is growing within this. Online Diwali shopping generated ₹1.15 lakh crore in festive sales during the 2025 season — roughly $13.7 billion — though it is but a fraction of total spend. The in-store experience remains central to how India’s consumers mark the festival.
What Diwali 2026 spending looks like
Diwali falls on November 8 this year, later in the calendar than 2025, which gives retailers a longer activation window and spreads consumer spending across an additional pay cycle.
The forward indicators are broadly positive. Hansa Research’s Festive Insights 2026 report finds that 95% of Indian consumers plan to spend more than usual this season. In fact, 45% expect to spend 25–50% more than last year, and 22% plan to spend over 50% extra. Not every indicator, however, points the same way. A LocalCircles survey of urban households projects festive spending to fall 6% in 2026, citing inflation and rising borrowing costs. But that measures planned budgets; Hansa captures stated intent. Indian consumers are entering this season with high aspirations and tighter wallets, spending more selectively, not less.
Category growth is shifting. Grocery is expected to grow 48–50%, beauty and personal care 35–40%, and quick commerce 110–120%, according to Redseer Strategy Consultants. Electronics, historically the anchor category for Diwali retail, are losing ground for a very specific reason: smartphone prices are up 21% in 2026 due to rising memory chip costs, and consumers are redirecting that spend. Mobile phones accounted for 35% of festive sales in 2025; that share has already fallen below 30% this year, according to Datum Intelligence.
What global retail is missing
The $83 billion projection captures India’s domestic market alone. It does not account for the estimated 32 million members of the Indian diaspora across the United States, the United Kingdom, Canada, the Gulf, and elsewhere, communities that celebrate Diwali with comparable enthusiasm and, in many cases, significantly higher disposable income than the average Indian domestic consumer.
Western brands have been slow to treat this as a strategic opportunity. Jimmy Choo has run dedicated Diwali capsule collections with consistency, ranking as the best luxury shoe brand in India in the Mercedes-Benz Hurun India Best of the Best Brands 2025 survey. Louis Vuitton launched a ‘Rani Pink’ India-exclusive footwear collection for the festive season. Gucci produced a gold edition of its Horsebit 1955 bag specifically for Diwali 2023. Beyond fashion, Swiss chocolatier Läderach and Maison Ladurée introduced Diwali-specific product lines in 2023, while Estée Lauder has run recurring Diwali activations in India. For a market growing at 25% annually, the overall engagement is simply not enough.
What global retailers are missing is timing. India’s luxury consumer base is growing faster than any comparable market, and whatever brands build recognition and ritual now — through product, activation and genuine cultural presence — will hold an advantage. Diwali carries for Indian consumers the same emotional and aspirational weight that Christmas holds in Western markets. So, taking advantage of the moment makes absolute sense.
What comes next
Diwali 2026 spending will be tallied by the end of November. The data will confirm what the trajectory has been signaling for years: that this is no longer a market event the global retail industry can afford to treat as secondary.
Brands that have been showing up consistently through product activation and genuine cultural presence, already know this. Cultural familiarity takes years to build and a single Diwali season cannot buy it. At 25% annual growth, the cost of waiting rises every year.