Key takeaways
- India’s retail real estate market is structurally undersupplied. New mall stock fell 73% in 2024 even as leasing volumes surged, compressing vacancies in prime locations across the country’s top cities.
- Organized retail accounts for just 12% of India’s $1 trillion retail market. The gap between that figure and the 80% share seen in developed economies defines the scale of the opportunity still ahead.
- The boom extends beyond retail. India’s luxury residential market is moving in lockstep, driven by the same wealth creation cycle and the same consumer, and signaling that this is, in reality, a structural shift.
For most mature retail markets, the story of the last decade has been one of contraction. Malls in the United States have spent years converting anchor store space into gyms and fulfilment centers. Across the Atlantic, European high streets have cycled through vacancy, reinvention, and vacancy again. The assumption, broadly shared, is that physical retail is a category in managed decline.
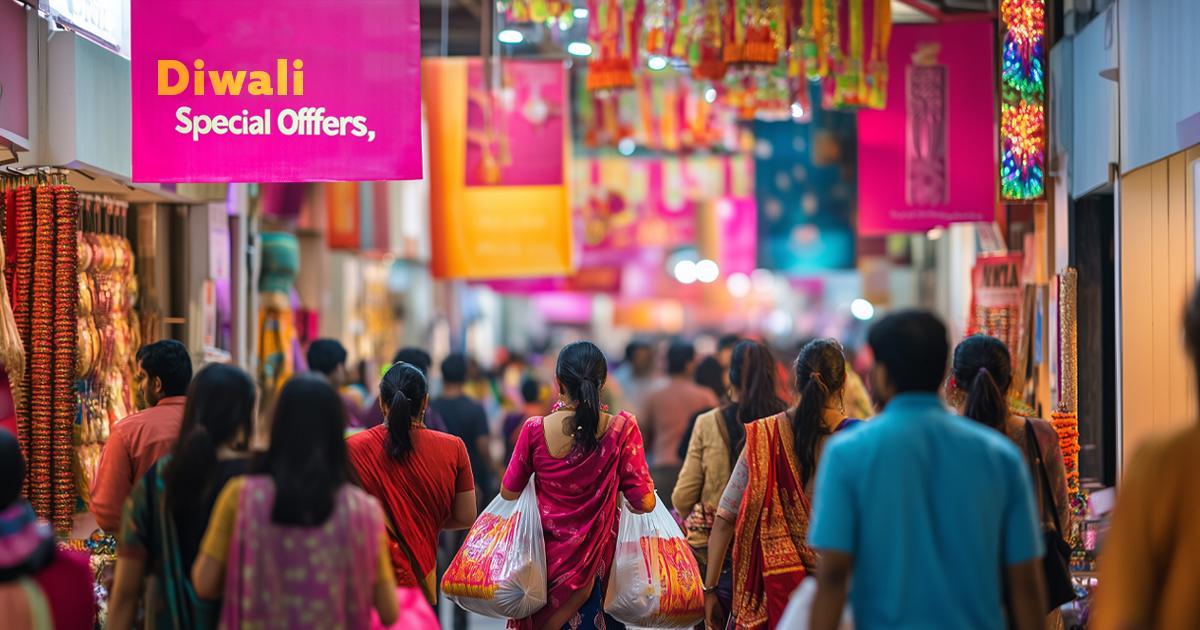
India never got that memo. The Indian retail real estate market never experienced a difficult period. Organized retail is still in its earliest chapters here, wealth is being created faster than the spaces built to absorb it, and demand for quality retail real estate is running well ahead of supply. That gap is what makes India one of the most watched and alluring real estate markets in the world right now.
A market running out of space
The numbers here are not the ones most analysts lead with. The headline figure — 92 million square feet of mall stock across India’s top seven cities at the end of 2025, according to JLL — sounds substantial. It is not, however, not by far, relative to demand.
What tells the real story is what happened to new supply in 2024: it collapsed by 73% compared to the previous year. Large-format retail development takes years to deliver, and demand simply outran the pipeline. The gap that opened up as a result has yet to close.
Apparently, India is a market where quality retail space is genuinely scarce. Vacancies in prime locations are compressing, and leasing volumes are climbing fast. Gross leasing across the country’s top seven cities grew 65% year-on-year in Q3 2025. Cushman & Wakefield projects total retail leasing will reach 10 to 11 million square feet in 2026, up from 7.8 million square feet in 2024. Between 2025 and 2030, approximately 60.9 million square feet of new mall supply is expected to enter the market, making it the largest infusion of retail space in Indian history.
That dynamic is both an opportunity and a warning. Especially for retailers, developers, and investors watching from the outside. The window to secure prime locations before supply catches up with demand is narrowing.
High streets and malls: Two winning formats
In most markets, the mall versus high street debate has a clear winner. Consumers either gravitate toward organized retail destinations or they return to street-level shopping, but rarely both at once, and rarely with equal conviction. India, on the other hand, is doing both.
According to JLL’s Q4 2025 data, high streets commanded a 48% share of total retail leasing activity in 2025, with shopping malls capturing 45%. The fact that high streets are leading in a market defined by mall development is not a minor detail. It points to something fundamental about how Indian consumers shop: they move across formats, across locations, with a preference for accessibility that no single retail format can satisfy alone.
Delhi, Bengaluru, and Hyderabad drove the bulk of this activity, accounting for 24%, 24%, and 23% of total leasing volume, respectively. All three are established, high-consumption cities, and all three are still absorbing demand way faster than new supply can arrive.
What the data tells you is that the Indian consumer is present on the high street and in the mall, often the same person on different days. You see, the market is absorbing both simultaneously and at scale.
The long game
The number that reframes everything about the Indian retail real estate market is, in fact, this: organized retail accounts for just 12% of India’s total retail market. In developed economies, that share sits at around 80%. The gap between those two numbers is where the real scale of India’s retail real estate opportunity lies.
India’s total retail market is valued at approximately $1 trillion. The organized segment — shopping malls, branded high streets, franchise retail — is still a fraction of that. The rest is unorganized: street vendors, small family-run shops, informal neighborhood markets that have defined Indian retail for generations. Between 2025 and 2030, approximately 60.9 million square feet of new mall supply is expected to enter the market across India’s top cities. That wave of new supply will expand the organized segment, but it will not close the gap. Not even close. What it will do is give brands and developers a foothold in a market that is structurally positioned to keep growing long after most other retail real estate markets have plateaued.
What does the bigger picture show?
India’s retail real estate boom does not exist in a vacuum. Alongside it sits a luxury residential market that is moving with equal, if not greater, force.
In June 2026, Oberoi Realty launched the first phase of Three Sixty North, a high-end residential project in Gurugram, near Delhi, with each unit priced between 200 and 300 million rupees. It sold out in two hours. The company received four times the demand it could accommodate. Oberoi Realty is now targeting 135 billion rupees in sales for the financial year through March 2027 — more than double its previous figure.
Oberoi is not alone. Prestige Estates Projects, another major Indian developer, is targeting a 43% jump in sales value this fiscal year. Across India’s top seven cities, average luxury housing rates rose from 14,530 rupees per square foot in 2022 to 20,300 rupees by December 2025.
The wealth being created in India right now is looking for places to go. It is going into premium apartments, and it is going into the retail destinations those same buyers frequent. The two markets are not connected by coincidence. They are being driven by the same consumer: wealthier, more aspirational, and more willing to spend than at any previous point in India’s economic history.
What does this mean for global retail?
The time to move on India is now, and the terms available today will not hold indefinitely. Grade A mall space is scarce, prime high street locations are filling fast, and the supply pipeline will not catch up with demand in the near term.
A consumer base of 1.4 billion people, an organized retail sector at just 12% penetration, and a wealth creation cycle expanding faster than the infrastructure built to serve it; these are the foundations of the Indian retail real estate market as it stands today. A decade from now, the market will most probably look entirely different. The organized segment may be larger, the supply gap might have narrowed, and the prime locations will be long gone.
Galeries Lafayette opened its first Indian store in Mumbai in November 2025. Louis Vuitton, Lululemon, and Panerai are among the 60 international brands that have entered the market in the past four years. They are ahead of a wave that is still building, and that wave has a long way to run.


