Key takeaways
- Global luxury is on track to grow approximately 4% in 2026 and 5–6% in 2027, but the recovery is not broad-based. Growth is concentrating among a smaller number of high-spending consumers, with 1% of shoppers now accounting for 27% of tax-free luxury spending globally.
- The Gulf region is holding its ground despite a dip in Middle Eastern visitor numbers. Spending by affluent Gulf consumers remained close to previous-year levels during 2026, while Saudi Arabia accounted for approximately 93% of GCC e-commerce investment in 2025.
- Desirability is increasingly earned. As aspirational consumers pull back, the brands gaining ground are those investing in authenticity, craftsmanship and experience over scale.
Global luxury is returning to growth, with the market expected to expand by approximately 4% in 2026 and strengthen towards 5–6% in 2027. Yet the recovery is unfolding very differently from previous cycles. Growth is becoming increasingly concentrated among affluent consumers, geographical performance is diverging more sharply, and value creation is shifting towards a smaller number of high-spending clients.
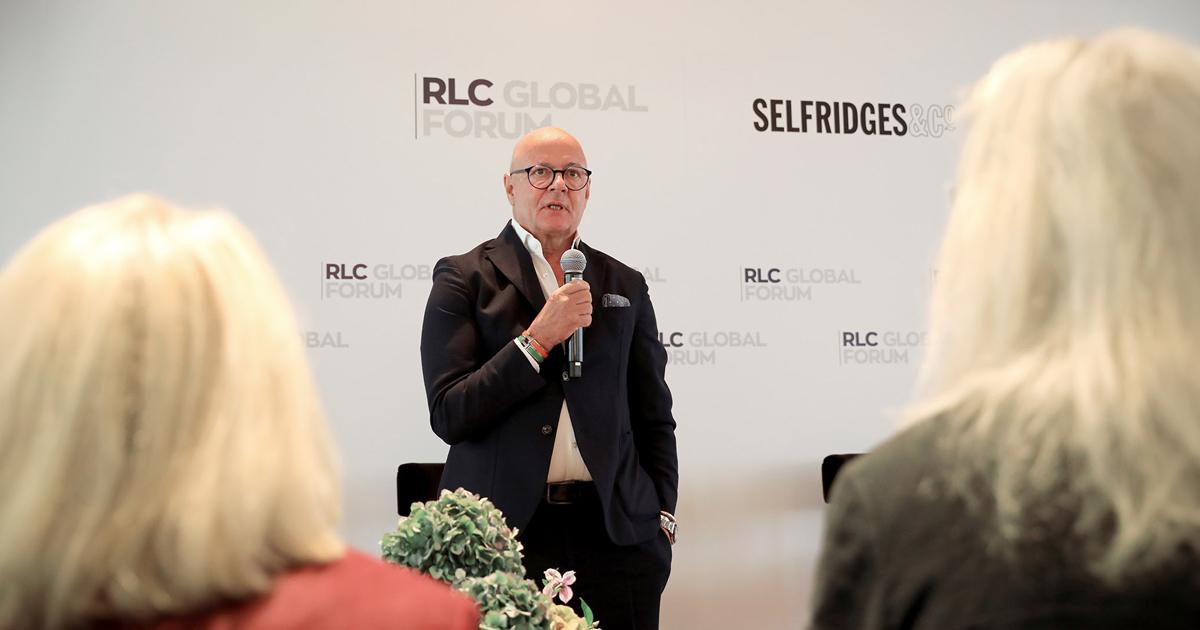
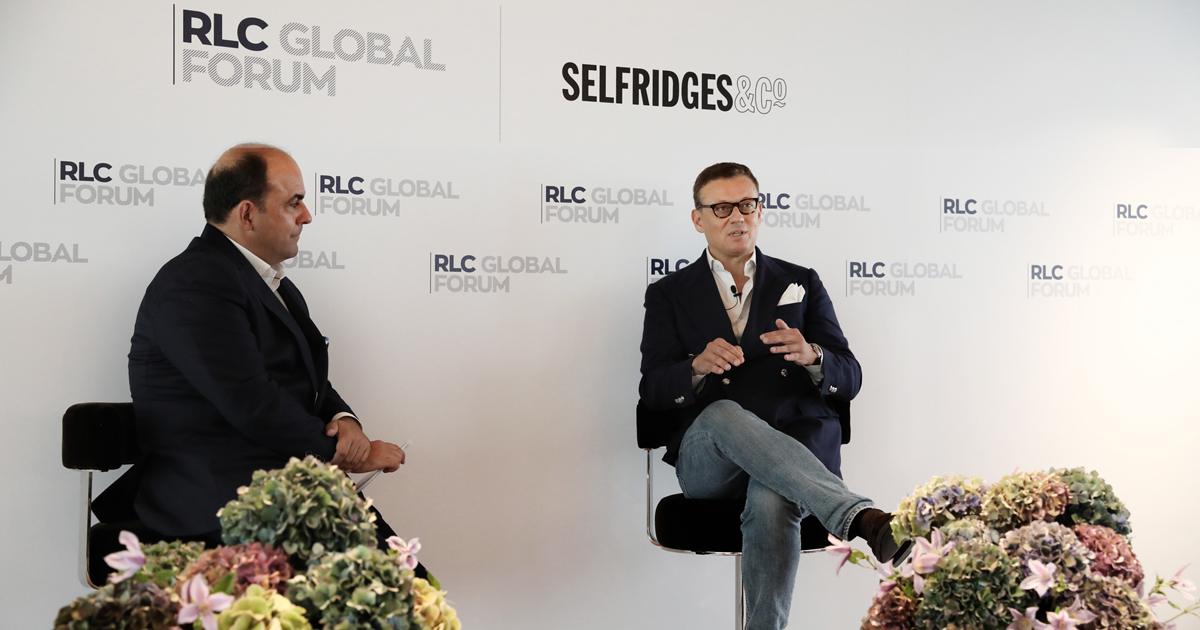
These were among the principal conclusions emerging from “The New Geography of Growth”, an executive leadership session convened by RLC Global Forum in partnership with Selfridges. Bringing together chief executives, investors and senior industry analysts, the discussions explored the structural forces reshaping global luxury demand as markets, consumers and investment patterns continue to diverge.
The United States has firmly established itself as the luxury industry’s primary growth engine, while China has entered a more measured phase of recovery following two years of contraction. Performance is also becoming more polarized across categories, with jewelry and hard luxury continuing to outperform as leather goods face mounting resistance from aspirational consumers following successive price increases.
“Most brands are now seeing high single-digit to double-digit growth in the market, supported by wealth creation, particularly from technology,” suggested Deborah Aitken, Senior Industry Analyst at Bloomberg Intelligence. “The next phase of luxury growth will depend less on broad consumer participation and more on attracting high-value clients.”
Global Blue data showed that across Europe’s leading luxury destinations, the number of ultra-affluent international shoppers has remained broadly flat — declining slightly in some markets—while spending per client has continued to increase. Among Europe’s highest-spending international visitors, U.S. shopper penetration has risen from below 10% historically to approximately 17%, with purchasing behavior correlating more closely with S&P 500 performance than exchange-rate movements. At the same time, travelers from Brazil, Mexico and Argentina are contributing an increasingly significant share of European tax-free luxury spending.
“The number of high-spending travelers has become more concentrated, but average spend continues to rise,” said Derrick Hardman, Regional Chief Operating Officer of Global Blue. “One percent of shoppers now account for 27% of tax-free luxury spending.”


Is the GCC luxury market rewriting its growth story?
The Gulf’s position in global luxury is shifting from dependent on inbound travel to something more structurally durable. Despite double-digit declines in Middle Eastern visitor numbers during parts of 2026, spending by affluent Gulf consumers remained close to previous-year levels, a pattern that aligns directly with the broader concentration thesis: the buyers who remain are spending more, not less.
The domestic investment picture adds another dimension. Bloomberg Intelligence data presented at the session showed Saudi Arabia accounted for approximately 93% of GCC e-commerce investment in 2025. Online retail across the region continues to grow faster than global averages despite relatively low market penetration, pointing to long-run structural potential. Dubai, meanwhile, has demonstrated the resilience of its luxury ecosystem through rebounding international tourism and its continued role as one of the world’s principal travel and retail hubs.
“We continue to see growth across the GCC, although it will come through different channels than before,” explained Deborah Aitken. “Tourism recovery is likely to take longer, but domestic investment and regional capital deployment continue.”
Can desirability be manufactured?
As spending becomes concentrated among a relatively small group of global consumers, destination retailers are rethinking how physical space is used, placing greater emphasis on private clienteling, hospitality, personalized services and curated experiences.
“Luxury is about more than buying a product. It is about creating moments people remember. Retail today is about creating happiness,” said André Maeder, Chief Executive Officer of Selfridges Group. “We want people to come for the experience, even before they decide what they want to buy.”
International retail destinations are also adapting to changing travel behavior, with experience becoming an increasingly important driver of destination choice for high-value travelers.
“Luxury today is no longer only about value. It is about hospitality, culture and the quality of the experience,” stated Sylvie Freund-Pickavance, Global Strategy & Business Development Director at Value Retail. “Travelers increasingly choose destinations that combine shopping with culture, hospitality and experiences.”
As consumers become increasingly selective, competitive advantage is becoming progressively less dependent on scale or physical expansion and increasingly linked to craftsmanship, creativity, authenticity and sustained cultural relevance.
“Desirability cannot simply be manufactured through marketing. It is earned through authenticity, creativity and consistency,” added Helen Brocklebank, CEO of Walpole.
Where does the conversation go from here?
The executive session also introduced “Uneven Futures”, the theme of the 2027 RLC Annual Forum, taking place in Riyadh on 1–2 February 2027.
“Growth is becoming more uneven and investment more selective,” said Panos Linardos, Chairman of RLC Global Forum. “Understanding why some markets, sectors and businesses accelerate while others stall is becoming a defining leadership challenge. That’s the thinking behind ‘Uneven Futures’, and the conversation we will continue in Riyadh next February.”
Explore the key moments, conversations and insights in the post-event report.